Could a Temporary Buydown Help Get Your Listing Moving?
Could a Temporary Rate Buydown Help Get Your Listing Moving?
A financing strategy that could help generate new interest—without reducing the price.
If you have a listing that is getting showings but isn't generating offers as quickly as you'd like, it may be time to look beyond a price reduction.
One option worth considering is a seller-paid Temporary Rate Buydown.
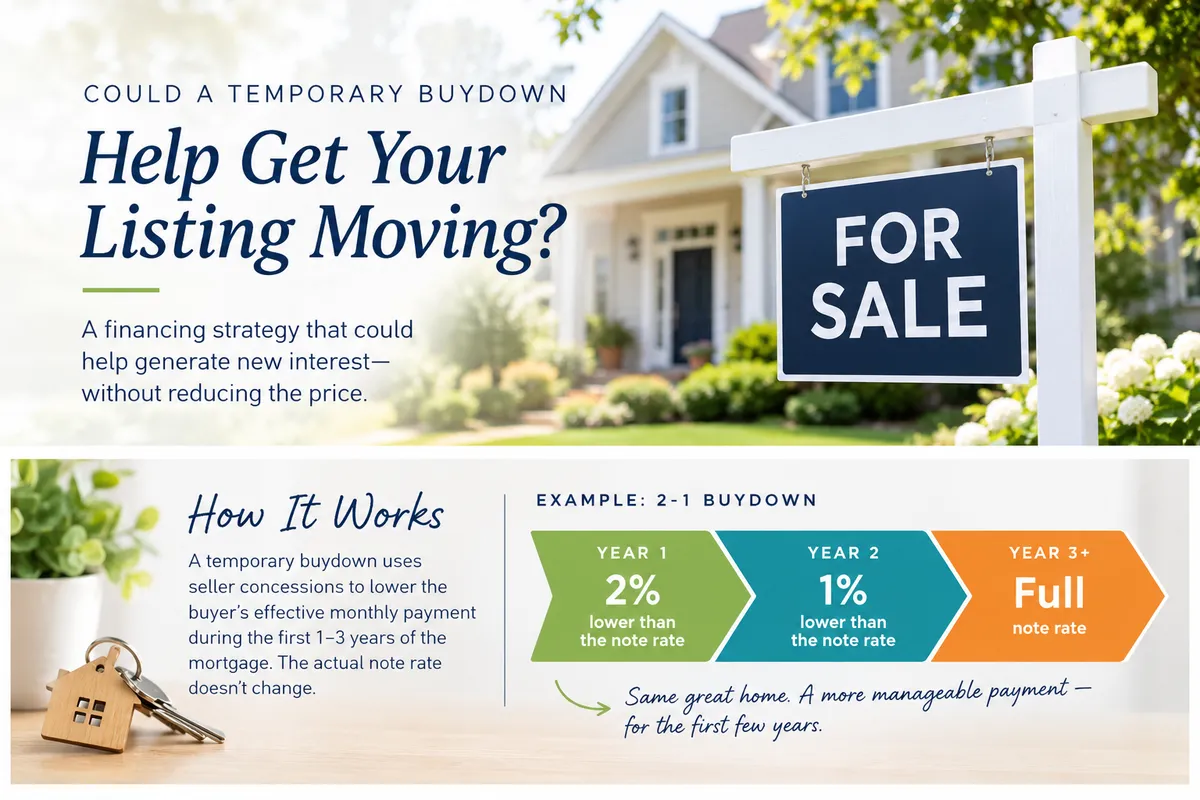
A temporary buydown uses seller concessions to temporarily reduce the buyer's effective monthly payment during the first 1–3 years of the mortgage.
That means you may be able to give buyers a meaningful payment incentive without lowering the list price.
How Does It Work?
Depending on the program, a temporary buydown can reduce the buyer's effective interest rate by up to 3% in the first year.
For example, with a 2-1 buydown:
Year 1: 2% lower than the note rate
Year 2: 1% lower than the note rate
Year 3+: Full note rate
The mortgage's actual note rate does not change. Instead, funds placed into a subsidy account are used to offset part of the buyer's payment during the buydown period.
The buyer must still qualify using the full note rate.
Why Should Listing Agents Care?
Because sometimes the issue isn't the house.
It's the monthly payment.
A buyer may love the property but hesitate when they calculate what today's interest rates mean for their monthly budget.
A seller-paid buydown gives you another conversation to have with your seller:
Instead of reducing the price, could we use a seller concession to make the financing more attractive?
Depending on the situation, this could:
Create a new reason for buyers to take another look
Help a listing stand out against competing properties
Make the monthly payment more manageable for buyers
Give buyers an incentive without simply cutting the sales price
Potentially help a listing that has been sitting on the market longer than expected
An Opportunity for Buyers' Agents, Too
Temporary buydowns aren't just a strategy for listing agents.
Buyers' agents can also consider a seller-paid buydown when structuring an offer.
If your buyer loves a home but is concerned about the monthly payment, a seller concession toward a temporary buydown may be worth exploring as part of the offer.
Instead of asking the seller to simply reduce the purchase price, you could structure an offer that gives the buyer greater payment relief during the first few years of homeownership.
This can be especially useful when:
Your buyer is payment-sensitive
The seller has room for concessions
You're competing with other offers and want to make your offer more compelling
The buyer would benefit more from payment relief than a small reduction in purchase price
You're negotiating on a listing that has been sitting on the market
The important part is to run the numbers before writing the offer. The best strategy will depend on the purchase price, loan amount, interest rate, loan program and applicable concession limits.
Another Tool for Your Offer or Listing Strategy
A Temporary Rate Buydown isn't right for every seller or every buyer. But when the numbers work, it can give you another strategy to consider before simply reducing the price—or walking away from a home your buyer wants.
Whether you're representing the seller or the buyer, I'm happy to run the numbers on a specific transaction and show you what a temporary buydown could look like.
Have a listing that needs a fresh strategy? Have a buyer who loves a home but needs more payment flexibility? Let's take a look at the numbers.
Let's Talk
Stephanie G. Smith
Senior Loan Officer | NMLS #1083107
Northeast Financial, LLC | NMLS #1172723
📞 (860) 272-4231
✉️ [email protected]
🌐 northeast-financial.com/ssmith
Temporary Rate Buydowns are subject to loan-program eligibility, applicable concession limits, underwriting requirements and other guidelines. Examples are for educational purposes only and are not a commitment to lend.