Love the Home but Not the Monthly Payment? A Temporary Rate Buydown Could Help.
Love the Home but Not the Monthly Payment? A Temporary Rate Buydown Could Help.
A smart financing strategy to help you ease into homeownership.
You've found a home you love. It's in the right neighborhood, has everything you've been looking for and fits your long-term goals.
But the monthly mortgage payment is giving you second thoughts.
Before you walk away or decide to wait for lower interest rates, there's a financing strategy you should know about: a Seller-Paid Temporary Rate Buydown.
This strategy could help you enjoy a lower initial mortgage payment for the first one, two or even three years of homeownership.
A Real-Life Example: Buying a Home While Paying for Daycare
I'm currently working with a wonderful family with two young children in daycare.
As many parents know, the cost of childcare can feel like a second mortgage!
They are ready to purchase their next home, but with two children in daycare, their monthly expenses are particularly high right now.
The good news? Their oldest child will start school next year, and their youngest will follow a year later.
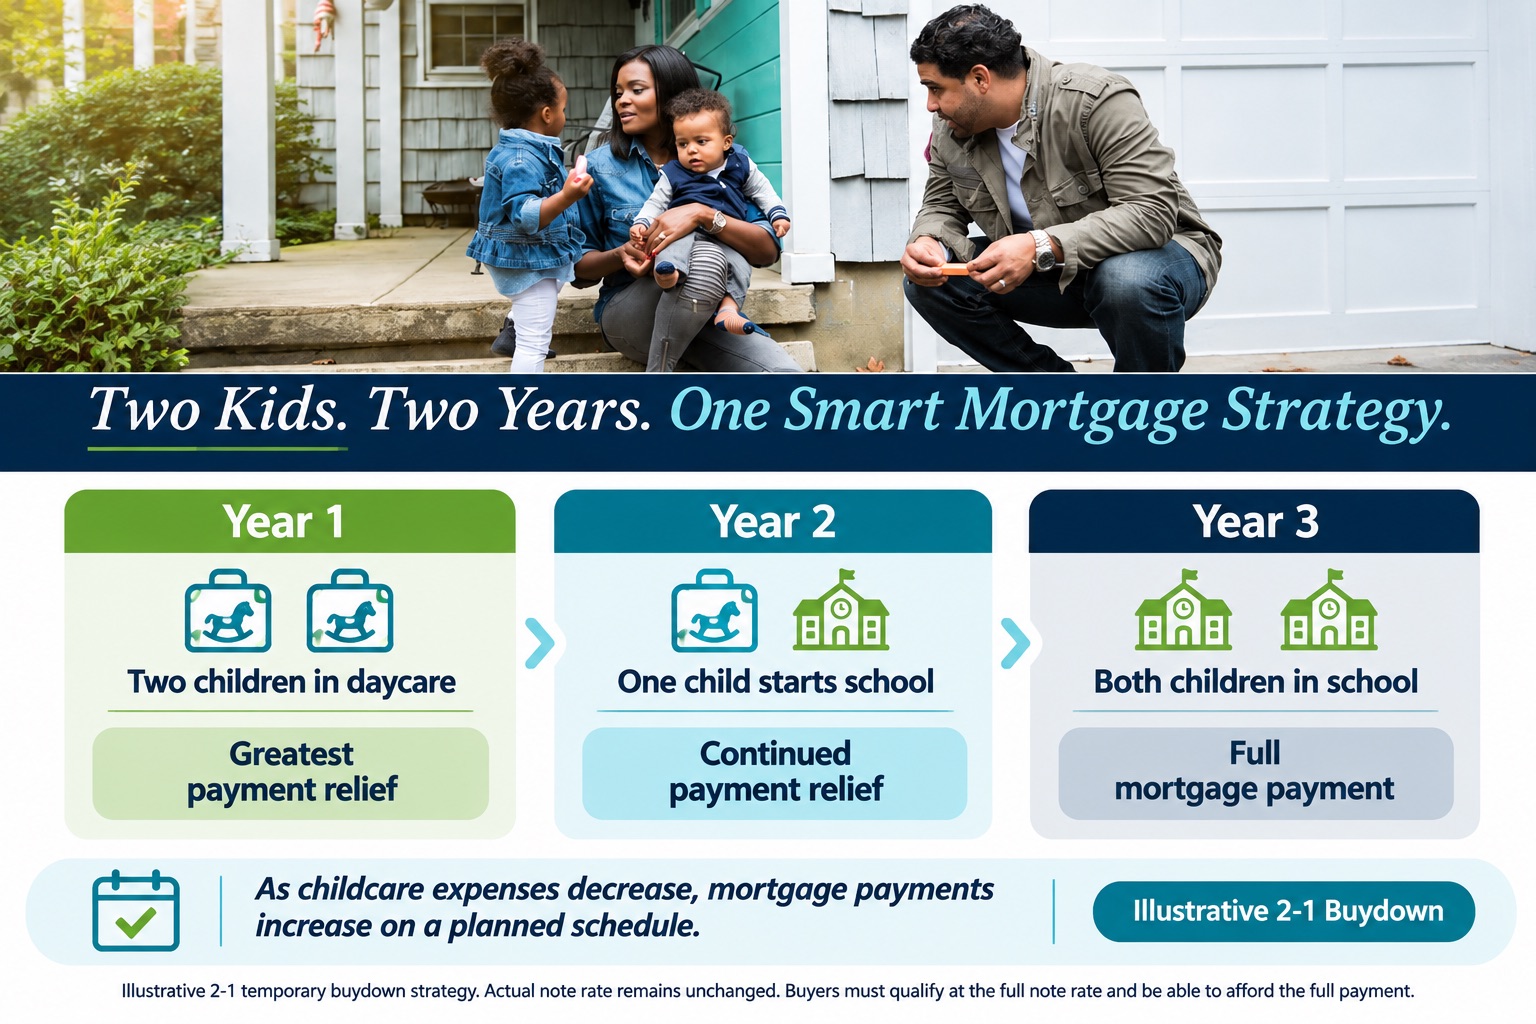
A seller-paid 2-1 temporary buydown could be an ideal strategy for their situation.
Here's why:
Year 1: They receive the greatest mortgage payment relief while both children are in daycare.
Year 2: Their mortgage payment increases, but their childcare expenses are expected to decrease as their oldest child starts school.
Year 3: They transition to their full mortgage payment as their youngest child starts school and their daycare expenses are expected to decrease further.
Rather than waiting another two years to purchase a home, they can explore a financing strategy that aligns with their family's changing expenses.
This is what thoughtful mortgage planning looks like. It's not just about today's interest rate—it's about understanding your financial situation, your goals and how your expenses may change over time.
What Is a Temporary Rate Buydown?
A temporary rate buydown allows qualified homebuyers to make a reduced monthly principal and interest payment during the early years of their mortgage.
Depending on the buydown option, your initial payment could be calculated using a rate up to three percentage points below your actual mortgage note rate.
And you may be able to negotiate for the seller to cover the entire cost of the buydown.
How Does It Work?
When a seller agrees to fund a temporary buydown, money is deposited into a dedicated account at closing.
Each month, that account covers the difference between your reduced principal and interest payment and your full scheduled principal and interest payment.
Your actual fixed mortgage rate does not change. Your payment increases on a predetermined schedule until you reach the full payment.
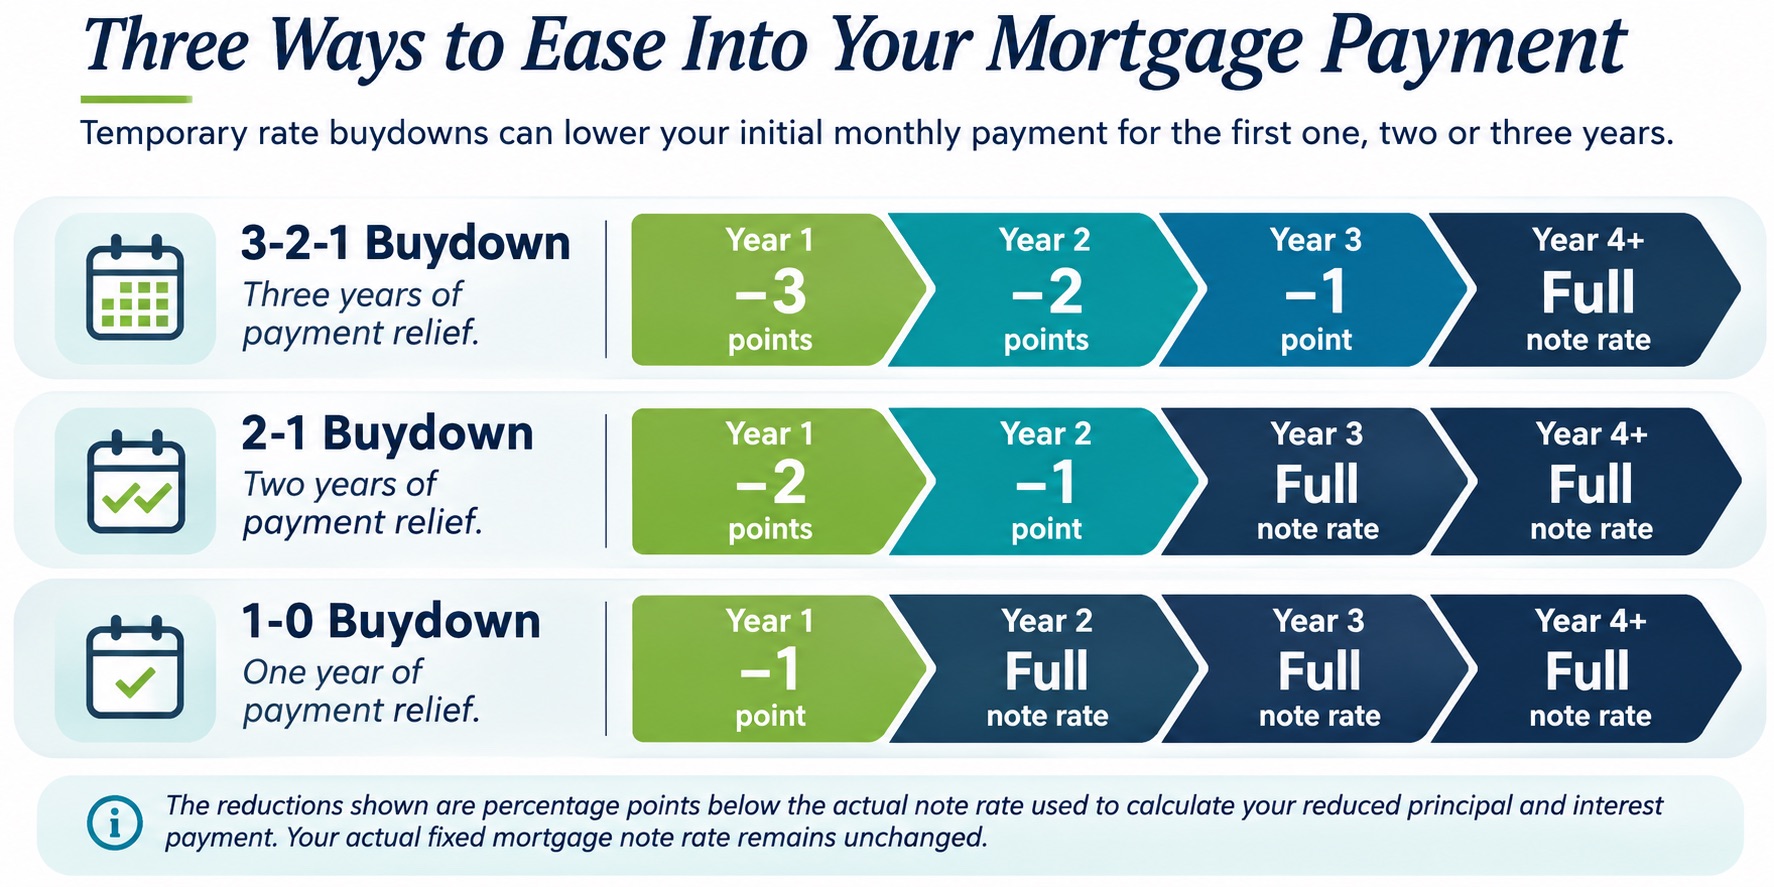
Three Ways to Ease Into Your Mortgage Payment
Buydown Option | Year 1 | Year 2 | Year 3 | Year 4+ |
|---|---|---|---|---|
3-2-1 | 3 points lower | 2 points lower | 1 point lower | Full |
2-1 | 2 points lower | 1 point lower | Full | Full |
1-0 | 1 point lower | Full | Full | Full |
The reductions shown are percentage points below the actual note rate used to calculate your reduced principal and interest payment. Your actual fixed note rate remains unchanged.
Who Could Benefit From a Temporary Buydown?
Families transitioning out of daycare are just one example.
A temporary buydown could also be a valuable strategy for buyers who want to:
Ease the transition from renting to homeownership.
Rebuild savings after making a down payment.
Manage moving and furnishing expenses.
Make improvements to their new home.
Manage temporary expenses that are expected to decrease in the coming years.
It's not about buying more home than you can afford. It's about making the transition into a home you can sustainably afford a little easier.
A Smarter Way to Structure Your Offer
Many buyers focus on negotiating a lower purchase price. But negotiating a seller contribution toward a temporary buydown could provide more meaningful monthly payment relief during the first few years than a modest price reduction.
This can be especially valuable when considering a home that has been on the market longer than expected or working with a seller who may be open to concessions.
Before submitting an offer, it's worth comparing a price reduction, temporary buydown, permanent rate buydown and seller-paid closing costs.
The best strategy is the one that aligns with your financial goals and priorities.
What If Interest Rates Come Down?
If interest rates decrease in the future, you may have an opportunity to refinance if you qualify and refinancing makes financial sense.
Depending on your buydown agreement, any remaining funds in your subsidy account may be applied toward your outstanding mortgage balance when you refinance.
However, you should never rely on the possibility of refinancing. Your full mortgage payment needs to work within your long-term budget.
Don't Let Payment Hesitation Keep You From Exploring Your Options
Finding the right home is only part of the process. Finding the right financing strategy is just as important.
As a Senior Loan Officer with over 15 years of experience, I help homebuyers explore financing strategies that align with their individual circumstances, goals and priorities.
Have a home in mind? Let's look at the numbers together.
I'll help you understand how much a temporary buydown could potentially reduce your initial monthly payments and work with your real estate agent to strategically structure your offer.
You may have more options than you realize!
Let's Connect
Stephanie G. Smith
Senior Loan Officer | NMLS #1083107
Northeast Financial LLC | NMLS #117273
📞 860.272.4231
✉️ [email protected]
🌐 northeast-financial.com/ssmith
Temporary Rate Buydowns are subject to borrower qualification, loan-program eligibility, seller agreement and applicable concession limits. Borrowers must qualify at the full note rate. Payment reductions apply to principal and interest only. Taxes, homeowners insurance, mortgage insurance and HOA dues are additional where applicable. Future refinancing is not guaranteed. This information is for educational purposes and is not a commitment to lend.
Mortgage Broker Only, Not a Mortgage Lender or Mortgage Correspondent Lender. Equal Housing Opportunity.